Loan Appraisal & the 3x Savings Collateral Rule
Enforce statutory borrowing limits, calculate debt-to-income ratios, and validate the cooperative 3x savings collateral multiplier.
1. Overview & Business Value#
This comprehensive operational guide details the architecture, business workflows, configuration parameters, and execution steps for Loan Appraisal & the 3x Savings Collateral Rule within SmartERP.
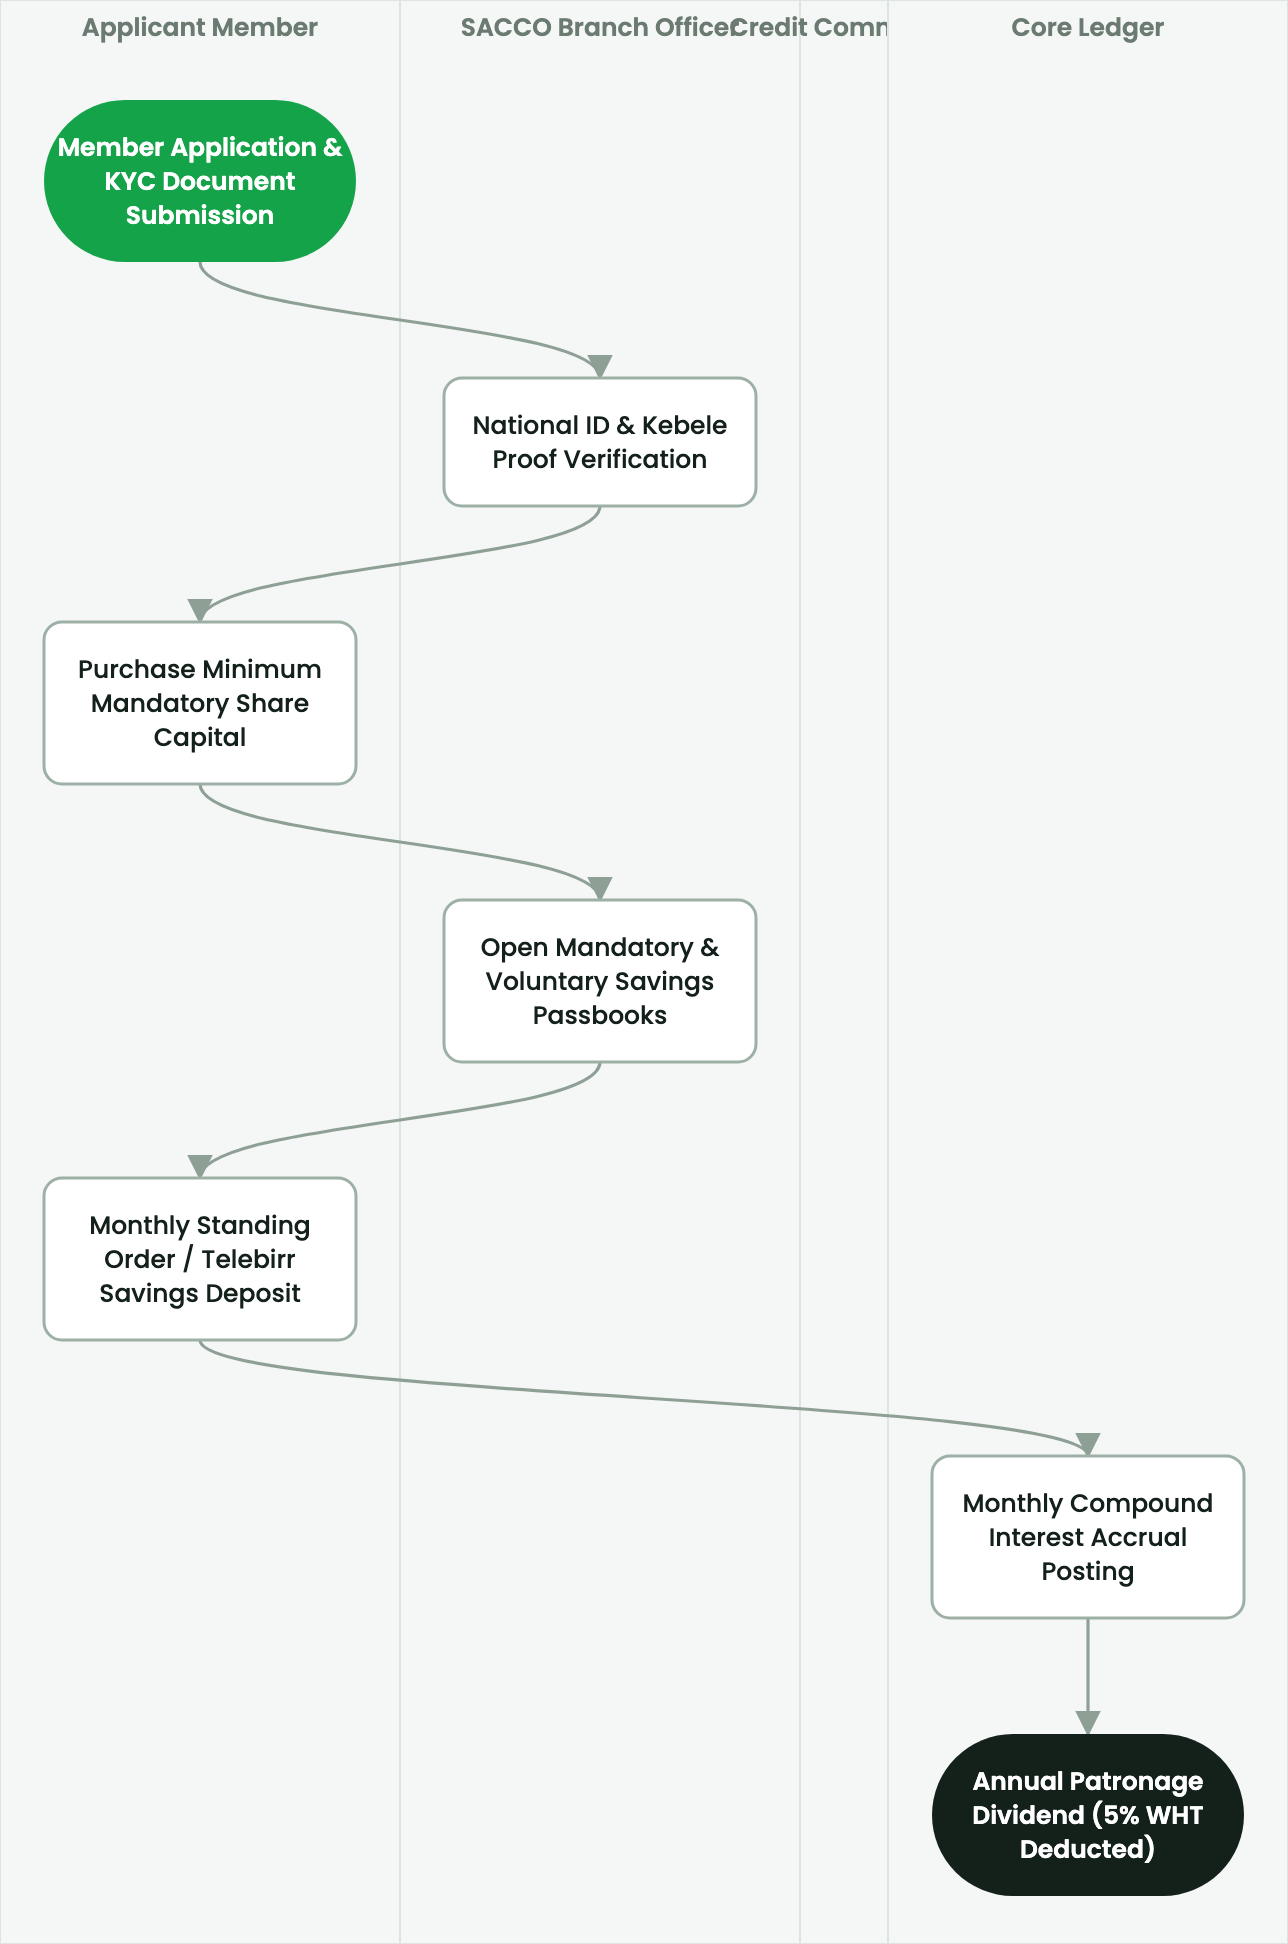
Enforce statutory borrowing limits, calculate debt-to-income ratios, and validate the cooperative 3x savings collateral multiplier.
2. Prerequisites & Security Access Groups#
- Required Modules:
smarterp_sacco_core, smarterp_equb, smarterp_loan_management - Security Groups:
SACCO Loan Officer(Technical ID:smarterp_sacco.group_sacco_officer)SACCO Credit Committee Member(Technical ID:smarterp_sacco.group_sacco_committee)SACCO General Manager(Technical ID:smarterp_sacco.group_sacco_manager)
- Master Data Dependencies: Member KYC profiles, share capital registers, savings product tiers, loan products with reducing-balance schedules, and Equb rotational pool configurations.
3. Step-by-Step Configuration & Execution#
Step 1: Navigating to the Interface#
- Log into your SmartERP instance at
https://smarterp.et/odoo. - Open the main App Switcher (grid icon in the top-left corner).
- Navigate to SACCO Core → Member Accounts; Loans → Active Loans.
Step 2: Operational Data Parameters & Controls#
Ensure all mandatory parameters comply with enterprise operational standards:
- Authorized Operator: Action executed under assigned RBAC permissions (SACCO General Manager, Loan Appraisal Officer, Cashier).
- Relational Integrity: Linked to upstream master records, approval requests, or transactional ledgers.
- Statutory & Quality Controls: Verified against Ethiopian statutory regulations and corporate governance standards.
Step 3: Operational Execution & State Progression#
- State Progression Gate: Advance record from Draft through Audited to Confirmed / Certified.
- Integrated System Impact: Automatically updates real-time operational states and posts financial/inventory journal moves.
- Audit Verification: System registers tamper-evident audit records logging user ID, timestamp, and cryptographic transaction digests.
The Statutory 3x Savings Multiplier Rule#
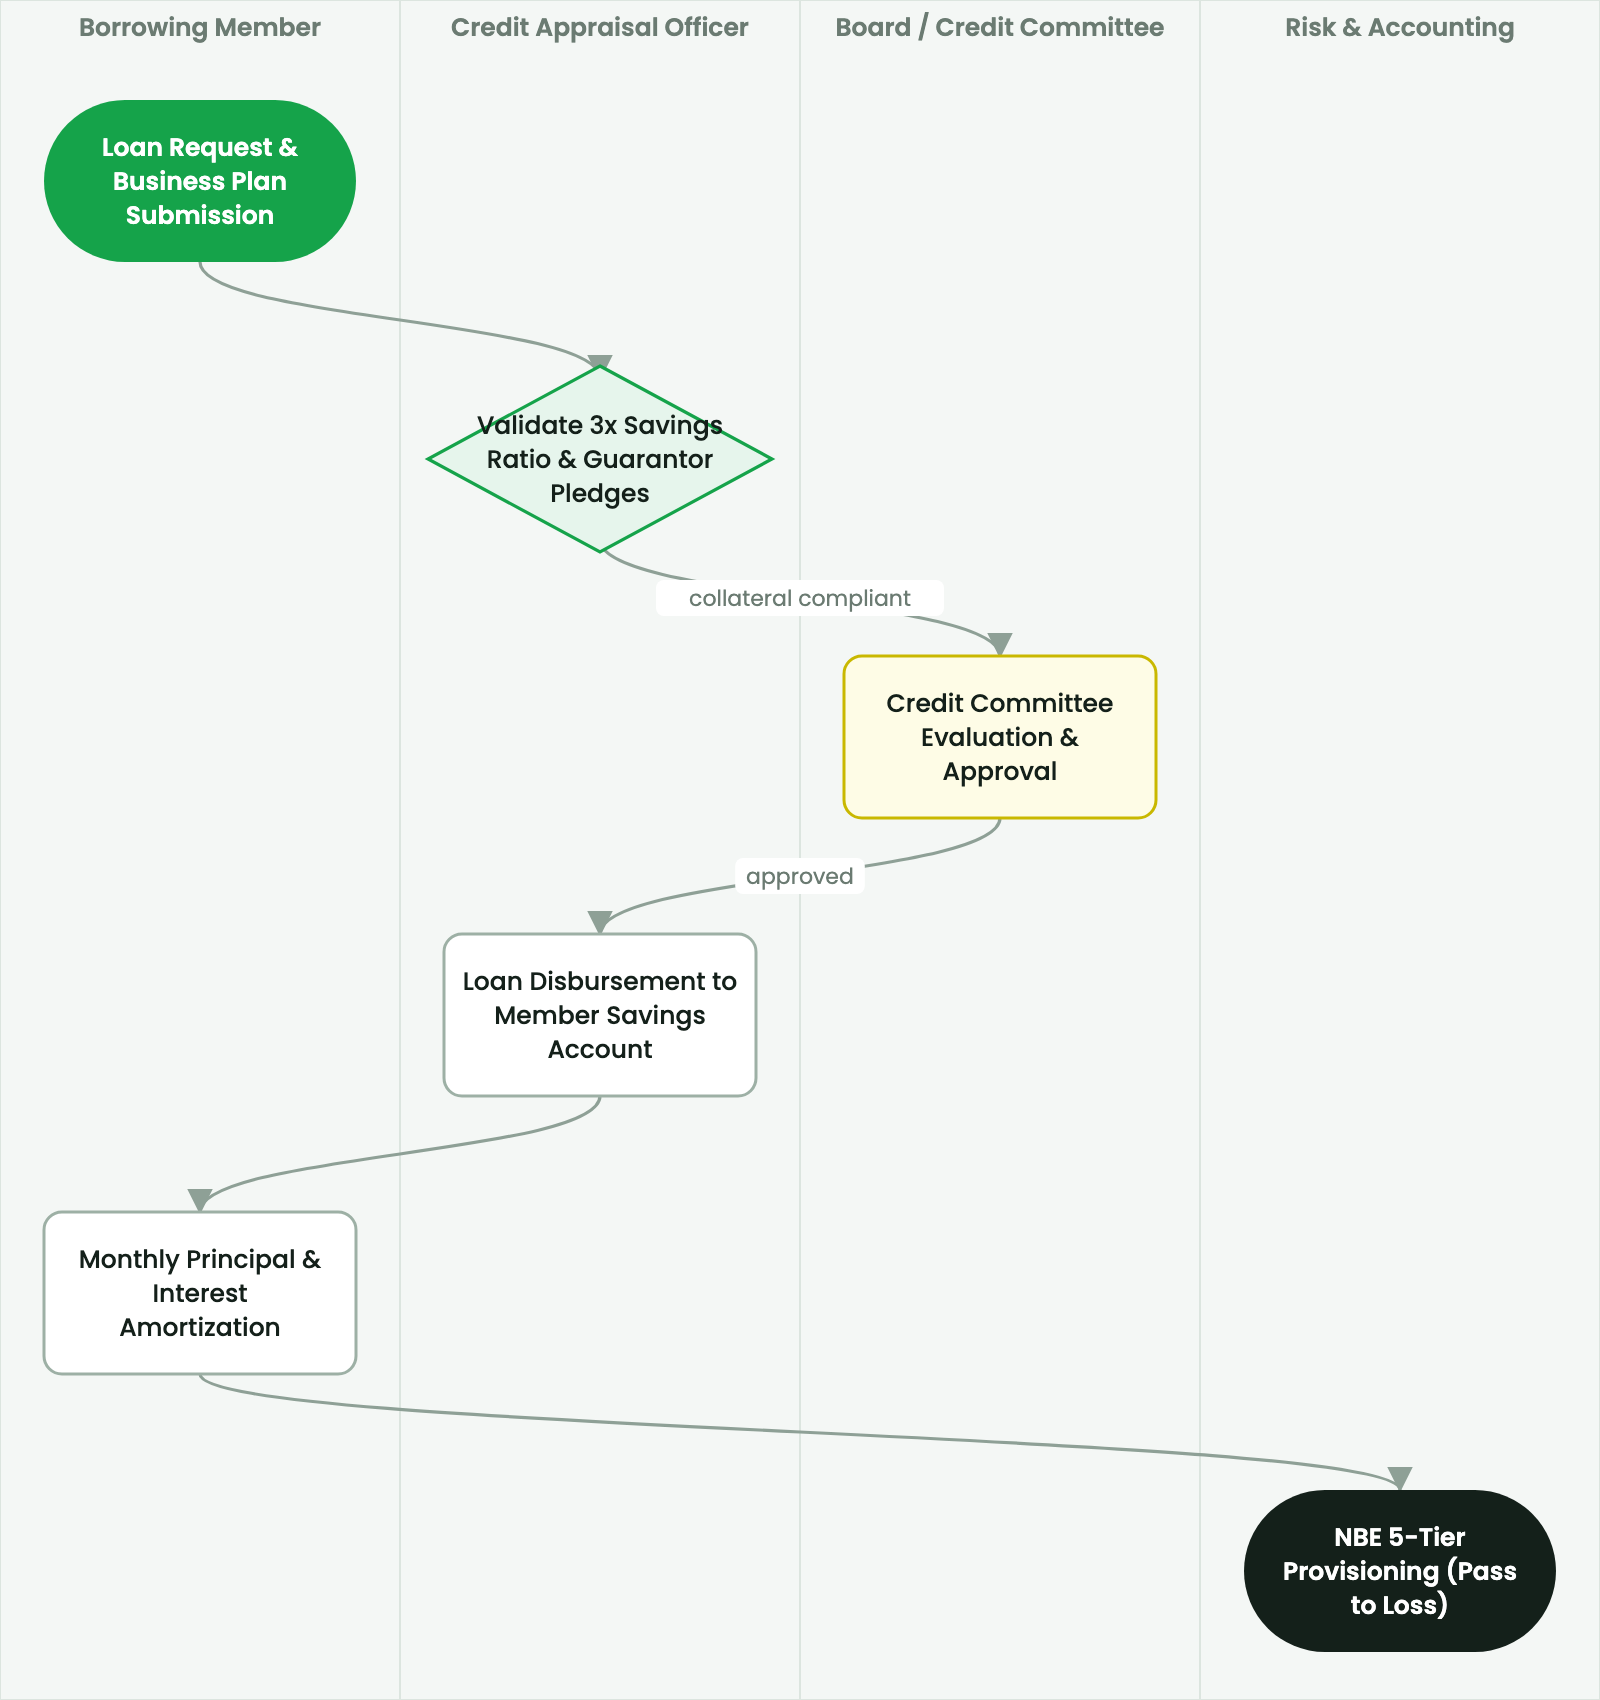
To safeguard cooperative solvency and member deposits, Ethiopian cooperative bylaws enforce the 3x Savings Rule:
$$\text{Maximum Eligible Credit} \le 3 \times \text{Unencumbered Member Savings}$$
$$\text{Available Borrowing Capacity} = 3 \times \left( \text{Total Savings} - \text{Pledged Guarantor Holds} \right) - \text{Existing Loan Balances}$$
The complete loan appraisal and NBE provisioning lifecycle:
Debt-to-Income (DTI) & Net Pay Verification#
In addition to savings collateral, workplace and institutional SACCOs must verify disposable salary:
$$\text{Debt-to-Income Ratio (DTI)} = \frac{\text{Total Monthly Debt Obligations}}{\text{Gross Monthly Salary}} \times 100\% \le 50\%$$
Under Ethiopian labor regulations, total deductions cannot reduce a worker's monthly take-home pay below one-third (33.3%) of their basic salary. SmartERP automatically blocks loan approvals where monthly repayment schedules violate this threshold.
Conducting the Credit Appraisal in SmartERP#
- Open SACCO > Loans > Loan Applications and click New.
- Select applicant member; the system automatically calculates:
- Cumulative unencumbered mandatory savings.
- Active loan balances across all cooperative facilities.
- Pledges made as guarantor for other borrowing members.
- Maximum allowable borrowing ceiling.
- If requested amount $\le \text{Capacity}$, the system displays a green Collateral Compliant badge.
- If requested amount $> \text{Capacity}$, the system blocks progression unless additional peer guarantors or physical collateral are attached.
- Click Generate Comprehensive Credit Appraisal Report.
4. Advanced Configuration Points#
- Automated Actions & Scheduled Tasks (Crons):
SACCO: Accrue monthly member savings interest(smarterp_sacco.ir_cron_savings_interest): Runs on the final day of each calendar month to credit interestLoan: Evaluate 5-tier NBE delinquency classification(smarterp_sacco.ir_cron_loan_delinquency): Runs nightly to compute loan loss provisions per NBE directivesEqub: Execute scheduled lottery draw(smarterp_sacco.ir_cron_equb_draw): Runs on defined pool cycle dates using provably fair random selection
- Custom Print Templates & Reports:
- Member Savings Passbook & Transaction Ledger
- Loan Amortization Schedule (Reducing Balance)
- NBE 5-Tier Delinquency & Loan Loss Provisioning Statement
- Annual Patronage Dividend Distribution Schedule
- Multi-Company Rules: Record-level security isolation under Company 1 (
Ashewa Technology Solutions S.C.), preventing cross-company ledger leakage across parent and subsidiary legal entities.
5. Comprehensive Troubleshooting Matrix#
| Error Symptom / Exception | Probable Root Cause | Corrective Action / Resolution |
|---|---|---|
Loan Blocked: Exceeds 3x savings ceiling | Requested loan principal exceeds 300% of member unencumbered savings balance. | Increase compulsory savings deposit or provide authorized co-signers with sufficient collateral. |
Equb Draw Blocked: Participant arrears detected | Selected Equb member has unpaid rotational dues in current or prior cycles. | Collect outstanding contribution payment before executing lottery draw. |
Share Capital Limit Error: Member exceeds 10% ceiling | Subscribed shares exceed statutory maximum under Proclamation No. 985/2016. | Restrict share allocation to maximum allowable 10% total cooperative equity threshold. |