ACSO Proclamation 1113/2019 & Fund Accounting Principles
In-depth analysis of ACSO cost categorization, direct program vs administrative definitions, and IPSAS fund accounting principles in Ethiopia.
1. Overview & Business Value#
This comprehensive operational guide details the architecture, business workflows, configuration parameters, and execution steps for ACSO Proclamation 1113/2019 & Fund Accounting Principles within SmartERP.
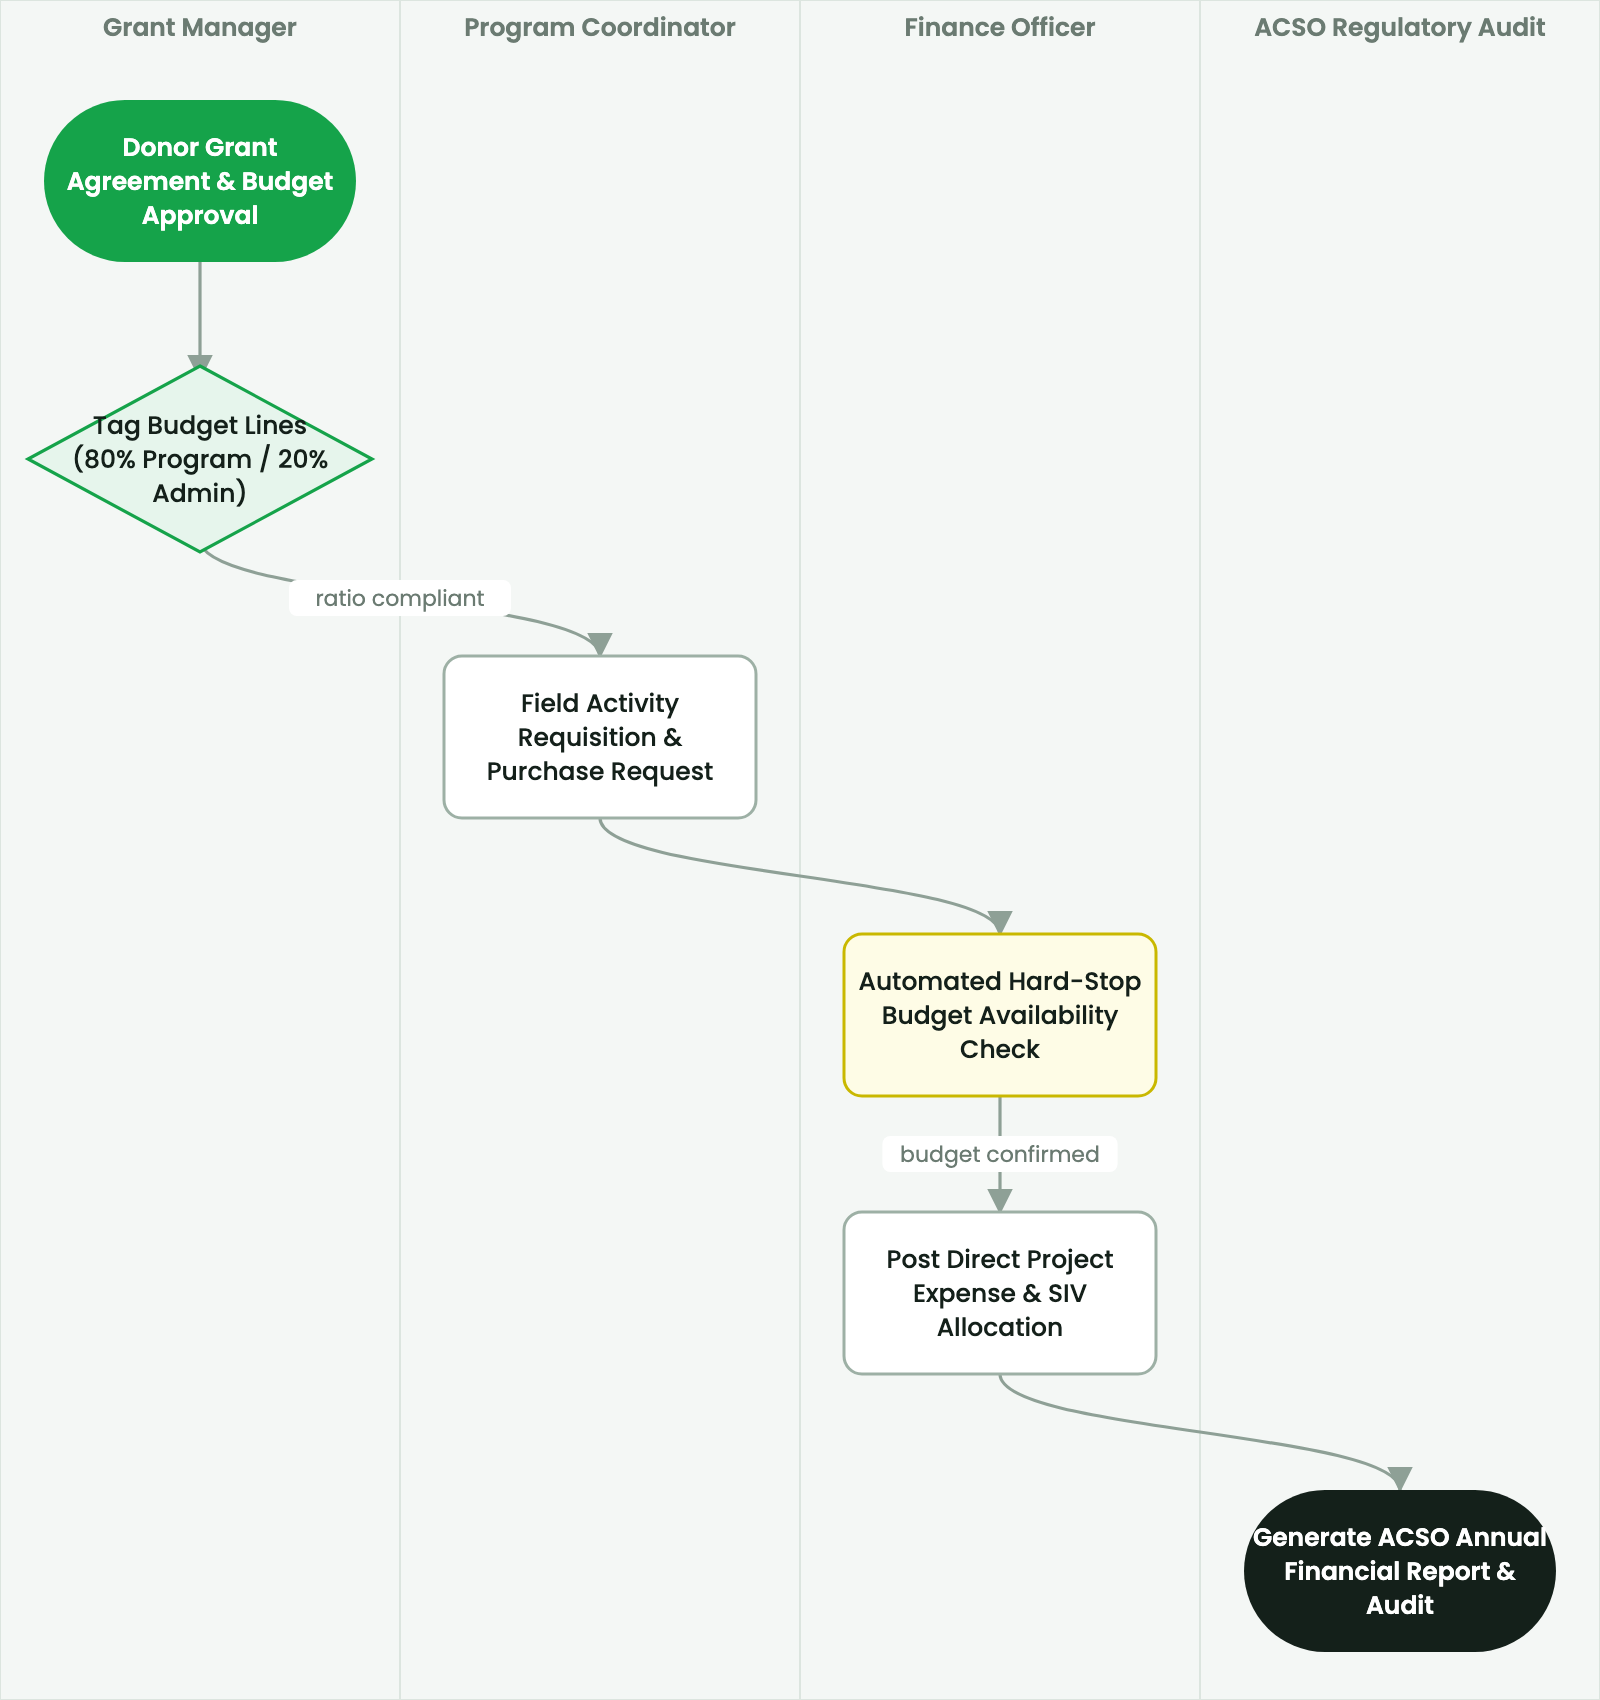
In-depth analysis of ACSO cost categorization, direct program vs administrative definitions, and IPSAS fund accounting principles in Ethiopia.
2. Prerequisites & Security Access Groups#
- Required Modules:
smarterp_ngo_grants, smarterp_humanitarian, smarterp_fund_accounting - Security Groups:
Grant Officer(Technical ID:smarterp_ngo.group_grant_user)Finance Director (NGO)(Technical ID:smarterp_ngo.group_grant_manager)Field Relief Distribution Officer(Technical ID:smarterp_ngo.group_field_officer)
- Master Data Dependencies: Donor profiles (USAID, EU, UN, FCDO), multi-currency grant agreements, restricted fund accounts, ACSO 80/20 cost allocation categories, and beneficiary rosters.
3. Step-by-Step Configuration & Execution#
Step 1: Navigating to the Interface#
- Log into your SmartERP instance at
https://smarterp.et/odoo. - Open the main App Switcher (grid icon in the top-left corner).
- Navigate to Grants → Active Grants.
Step 2: Operational Data Parameters & Controls#
Ensure all mandatory parameters comply with enterprise operational standards:
- Authorized Operator: Action executed under assigned RBAC permissions (Country Director, Grant Manager, Compliance Officer, M&E Specialist).
- Relational Integrity: Linked to upstream master records, approval requests, or transactional ledgers.
- Statutory & Quality Controls: Verified against Ethiopian statutory regulations and corporate governance standards.
Step 3: Operational Execution & State Progression#
- State Progression Gate: Advance record from Draft through Audited to Confirmed / Certified.
- Integrated System Impact: Automatically updates real-time operational states and posts financial/inventory journal moves.
- Audit Verification: System registers tamper-evident audit records logging user ID, timestamp, and cryptographic transaction digests.
The Mandatory 80/20 Cost Ratio Rule#
Under Section 63(2) of ACSO Proclamation No. 1113/2019, all civil society organizations registered in Ethiopia must allocate their operational expenditures according to statutory ratios:
$$\text{Program Expenditure Ratio} = \frac{\text{Direct Program Costs}}{\text{Total Operational Costs}} \times 100\% \ge 80.0\%$$
$$\text{Administrative Expenditure Ratio} = \frac{\text{Administrative & Support Costs}}{\text{Total Operational Costs}} \times 100\% \le 20.0\%$$
Failure to maintain this ratio over the fiscal year triggers formal regulatory warnings, administrative penalties, or potential revocation of the organization's operating license.
Statutory Cost Classification Matrix#
SmartERP automatically tags every general ledger expenditure line with its statutory ACSO category:
| Expenditure Item | ACSO Statutory Tag | Classification Rationale |
|---|---|---|
| Beneficiary Food & Relief Supplies | Direct Program (80%) | Tangible goods delivered directly to target community beneficiaries. |
| Field Officer Salaries (Dedicated Project) | Direct Program (80%) | Time spent directly implementing field activities verified by timesheets. |
| Project Monitoring & Field Travel | Direct Program (80%) | Transport, per diem, and vehicle fuel consumed during field project monitoring. |
| Headquarters Rent & Executive Salaries | Administrative (20%) | General organizational overhead, Country Director, HR, and legal salaries. |
| Annual Statutory Financial Audit | Administrative (20%) | General organizational compliance and administrative audit expenses. |
| HQ Office Utilities & Board Meeting Costs | Administrative (20%) | General central administration and governance expenditures. |
IPSAS Restricted vs. Unrestricted Fund Accounting#
SmartERP segregates institutional capital into discrete funds:
- Restricted Donor Funds: Grant agreements with institutional donors (USAID, EU, FCDO, UN agencies, Global Fund) where resources are legally bound to specific project activities, locations, and timeframes.
- Unrestricted Core Funds: General public donations, membership dues, and unrestricted private philanthropic contributions that support central organizational development.
4. Advanced Configuration Points#
- Automated Actions & Scheduled Tasks (Crons):
NGO: Calculate ACSO 80/20 cost ratio compliance(smarterp_ngo.ir_cron_acso_ratio): Runs weekly to flag any operational overhead drift above 20% limitGrants: Reconcile foreign currency funding variance(smarterp_ngo.ir_cron_fx_reconcile): Runs monthly to revalue restricted foreign currency bank accounts
- Custom Print Templates & Reports:
- ACSO Statutory Annual Financial Statement (80/20 Rule)
- Donor Financial Expenditure Report (Multi-Currency)
- Beneficiary Relief Distribution Voucher (Model 20 SIV)
- Time-and-Effort Personnel Timesheet Allocation Summary
- Multi-Company Rules: Record-level security isolation under Company 1 (
Ashewa Technology Solutions S.C.), preventing cross-company ledger leakage across parent and subsidiary legal entities.
5. Comprehensive Troubleshooting Matrix#
| Error Symptom / Exception | Probable Root Cause | Corrective Action / Resolution |
|---|---|---|
ACSO 80/20 Violation Block: Administrative overhead exceeds 20% | Cumulative overhead costs exceed statutory ceiling established under Proclamation No. 1113/2019. | Reclassify direct project support expenses to program operational accounts or restrict general administrative spending. |
Budget Burn Halt: Grant line item allocation exhausted | Committed purchase or payroll expense exceeds approved donor line envelope. | Submit a formal grant budget reallocation or amendment request to the donor. |
Duplicate Beneficiary Error: ID already claimed in cycle | National ID or biometric record already logged for current distribution cycle. | Audit beneficiary registration records and confirm identity against Kebele verification list. |